I heart Nixie tubes

The economic consequences of the referendum that wasn't
As I speculated yesterday, Prime Minister Papandreou explicitly said today that his main rationale for calling a referendum was to putt a stop to speculation that Greece is considering exiting the Eurozone. The chain of events that led to the referendum being called off demonstrated beyond doubt that the political classes will be keeping Greece in the Euro at all costs.
The fact there is now a credible commitment is very important. It means that some of the funds that have exited the country will find their way back to its banks and its economy, it means that bond investors need not fear Greece inflating its debt away or engaging in unilateral funny business, and it means that a great source of uncertainty has been dealt with.
This is not to say that staying the Euro is the right course of action for Greece. But since this seems to be what a majority of the Greek people want, making a binding commitment is the right way to go. There will be more investment, lower spreads, and an increased willingness of the rest of the EU to engage constructively.
Forget sovereign debt, think sovereign equity
Yes, it's a bit too late for Europe now, but moving forward this could be a useful bit of financial innovation.
Sacrifice trade union to save the Euro
Greece and Ireland need to depreciate their currencies, but exiting the Euro is unworkable for either of them. Extraordinary times call for extraordinary measures, so they could both temporarily introduce import tariffs for EU products, as well as potentially recycle some of the money generated to export tariffs.
Imports go down, exports go up, GDP increases, deficit goes down. Of course this doesn't work in the long-run the way depreciation would, but it would work a treat as a short-run stimulus and deficit-reducing measure.
Stata is blogging
Stata now has an official blog, Not Elsewhere Classified. And here's a list of a few unofficial ones.
Development is mostly not about aid

Whether you believe aid is effective or not, it has always struck me that, as a quantitative matter, it is a drop in the ocean. I am not saying that we should abandon aid; I am convinced it mostly makes things better. What I am saying, however, is that given how little it is and how widespread poverty is, the effect on national-level indicators can only be very, very small.
While aid can realistically only ever be a small part of the solution, other policies pursued by rich countries can have very widespread effects, and have perhaps received less attention than is warranted. In other words, we may be giving x euros in aid, but how much are we taking back by pursuing a Common Agricultural Policy? How much aid would a country have to give to make up for the effect on the poor of tight immigration policies?
The excellent Owen Barder links to a worthwhile attempt to rank rich countries according to how well they perform on development along these dimensions:
Though the effects of aid on development are uncertain, there is a huge amount that industrialised countries can do – or not do – which affects how quickly countries develop. The policies of rich countries on trade, investment, migration, the environment, security and technology can make a huge impact on how quickly poor countries are able to develop. Yet we tend to judge industrialized countries too much according to how much aid they give, and too little to how they behave in all these other ways.
The Center for Global Development provides an essential service by ranking the rich each year so we can see how we are doing. They use a series of quantitative measures on all these dimensions to create a composite picture of how a country’s policies affect development.
The 2010 results are now in. An excellent effort; I hope the next step is an attempt to monetize the value of the different policies pursued. However arbitrary this exercise may be, it will be another step in going beyond a qualitative understanding of the effect of aid, trade policies, etc, allowing us to better focus our collective efforts.
Empathy is the opposite of Utopia
A beatiful presentation by Jeremy Rifkin:
Eat your heart out, Powerpoint.
Nicaragua invades Costa Rica due to Google error
A Nicaraguan military commander recently invaded Costa Rican territory, and ordered troops to take down a Costa Rican flag and replace it with Nicaragua's. Was this the work of a brash commander, going rogue on his superiors? A new policy of Nicaraguan imperialism? Neither. The incident was caused by an error in Google Maps. [...] commander Eden Pastora blamed the incursion on a misleading border on Google Maps that was off by some 3000 meters.
La Nación points to a disparity between the borders on Bing and Google. We've highlighted the area in question:
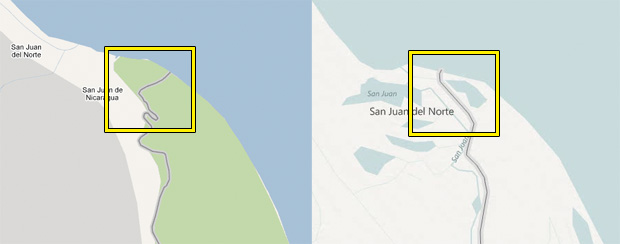
Thanks Austin Carr.
The night they burned government bonds
As I've noted before, one thing I've learned from this recession is that it's not as easy to increase the money supply as I thought.
This is Mark Thoma. But how about a big bond bonfire? (call it a bondfire if you must) How about direct financing of government debt?
I never got why Japan's lost decade was accompanied with such an explosion of government debt. The way I see it, below target inflation (let alone deflation) is a license to print money, and if the banks will do nothing with it, then the government should.
We seem to have forgotten the oldest trick in the book.
The Star Wars alphabet

Joe Wight has created the Kawaii Star Wars alphabet, with a different character for each letter of the alphabet. D, of course, is for that mean-looking fella above.
HT (and a full list of the letters in alphabetical order) Designers Couch.
Quitting smoking
I quit smoking four days ago. I am (was?) a very keen smoker, but after ten happy years of inhaling burnt tobacco I felt that the risk of cancer was starting to outweigh the pleasure of smoking.
Well, I said I quit, but I need to qualify that. I have not decided to quit for ever; I have only decided to quit for three weeks, and I will then evaluate whether I want to continue abstaining from smoking. This helps for two reasons:
- Quitting for three weeks is easier than quitting for ever. The former is a project I was willing to undertake; the latter sounded (and still sounds) too daunting to attempt.
- My nicotine addiction has already subsided somewhat, and will have subsided a lot more by the end of week three. So when at the end of week three I pose the question of what I want to do next, I'm more likely to opt for the 'quit' than the 'restart' option compared to making that decision at the height of my addiction.
Trick number three, I've started telling people - I find it hard, and painful, to break commitments and go back on my word, and even though I'm not really making any explicit commitments or promising anything to anyone, announcing that I'm undertaking this project creates expectations and I do not want to disappoint. Trick number four, I'm buying myself an iPad for Christmas, but if and only if I am still a non-smoker in two months' time.
The self-deception is, of course, crystal clear. But so far it's working.
Crazy, post-midnight thoughts on fiscal and monetary policy
When inflation is too low and you've hit the zero bound on the monetary side, and debt is too high to do anything on the fiscal side, you need to break the last taboo: direct financing of government debt by the Fed.
The only thing the Fed needs to do is to announce it fully intends to keep x amount of government bonds purchased under QE in its books till maturity - with the benefit naturally accruing to the Treasury. There would need to be some clarity on exact numbers so that nobody panics, but that's basically it.
A crazy idea - but note that this is merely a quantitative, not qualitative, deviation from the standard arrangement (even in normal times).
Debt to the penny
That's US debt held by the public tracked in real time since 1993, and it stands at 9,017,482,214,669.27 as of two days ago.
The Chinese seem to be holding about 10% of that, although the true figure may be somewhat higher - according to the table, the per capita holdings of Luxembourg stand at an astounding $200,000.
Friday Special 141
Why do the credit rating agencies move the sovereign debt market?
Markets play a simple yet crucial role: they price (or 'rate') assets, so as to ensure societal resources are allocated efficiently.
Markets do this better than any other institution yet devised because people need to put their money where their mouth is; it is not enough to say 'I think Greece will default' - if you are going to have an influence on the price, you have to be willing to take the risk of losing money if your opinion turns out to be wrong, and you would only do that if you have confidence in your information and analysis. That way, the price of different assets, including sovereign debt, is determined by the people with the best information (or, as is the case when it comes to extremely deep and liquid markets such as sovereign debt, the best ability to process the information that is freely available to all).
So, it is a serious perversion of this basic principle when the credit ratings agencies spend 60,000 dollars a year (that's the annual wage of a junior analyst) on analyzing Greek debt while investing exactly $0 on it, yet the effect they have on the price of that debt is equivalent to their controlling billions in funds. What the hell does it mean to 'rate debt'? Isn't this what the market is supposed to be doing by setting the price?
This state of affairs is so striking that I have to repeat this again. Markets work because people put their money on the line: ratings agencies don't. Furthermore, information on sovereign debt is abundant and the agencies have no informational advantage whatsoever (not to mention an appalling ratings record). Giving dodgy ratings to obscure CDOs is one thing, but rating sovereign debt should have had no effect on its price - information is aplenty.
I'm trying to work out a model as to why real market participants (you know, the ones with money on the line) don't completely discount the agencies' credit ratings of sovereign debt. Where I've got to so far implies that ratings agencies can only have a destructive effect, leading the market away from the efficient price: since the ratings do not reveal any new information (as I said, info on sovereign debt is abundant), the only reason they can move the price of debt is because they give an opportunity to smart money to profit at the expense of dumb money - money that is too stupid to rate sovereign debt independently, or is restricted from investing in debt below a particular rating.
I repeat: this is seriously messed up. Do the credit agencies have access to superior information on Greek debt compared to everyone (indeed anyone) else? No. Does the $60,000/ year S&P team analyzing Greek debt have such amazingly better insights than the collective might of analysts of hundreds of funds and banks across the globe? Hell no. Then why in the name of all that is folly does what S&P say affects the price of sovereign debt to such an extent?
And let me repeat a crucial point in case it wasn't made clear (a lot of repetition in this post, but this is what happens when your blogger starts getting a distinct feeling that either he has gone crazy or the rest of the world has). Don't try arguing that even if the credit ratings agencies don't have their money on the line they have their reputation to worry about - in case you just arrived on our beautiful planet from somewhere in the outer universe, they seriously messed up with CDOs with no effect whatsoever on their credibility and their ability to make money (there is a word for companies that can provide a crappy service and stay in business: they are called monopolies).
All in all, credit rating agencies have a destructive influence. They facilitate speculation at the expense of market efficiency, creating or reinforcing herd effects where market participants try to outfox the 'bigger idiots' rather than aim for the efficient price, seriously distorting the essential role of the market in accurately pricing assets. They risk nothing when pontificating on the value of different assets, and they add nothing real to the stock of available information - just a focal point for speculation. Furthermore, they are so embedded in the system - with funds having restrictions in their constitution restricting what they can invest in depending on its credit rating - that it's difficult to see a way forward.
We can start by pointing out the absurdity of the situation.


